



Written by Melody Webb for Haus Realty & Management
Category: Military Relocation
Short answer: Perdido Key can be a good purchase for a military family that prioritizes beach living, resort amenities, or a future vacation rental. However, it isn’t the most practical choice for every NAS Pensacola PCS. The Key generally means a longer and less predictable commute, higher flood and wind-insurance exposure, and more complicated rental rules than many mainland neighborhoods.
For families focused on a manageable daily drive, a yard, predictable monthly costs, or a long-term rental after the next transfer, the Perdido mainland or neighborhoods closer to NAS Pensacola may be a better fit. For buyers who value coastal lifestyle above convenience and understand the insurance and ownership costs, Perdido Key may be worth considering.
Is Perdido Key practical for a NAS Pensacola commute?
A planning estimate from Perdido Key to NAS Pensacola is approximately 25 to 30 minutes in ordinary conditions. That can change with the exact property, base gate, time of day, weather, road work, and seasonal beach traffic. The drive is not necessarily unreasonable, but it is longer than the commute from areas such as Navy Point, Warrington, or parts of West Pensacola.
That distinction matters during a PCS. A military family may be balancing:
- Early reporting times and duty schedules
- School drop-offs and pickups
- Medical appointments
- Shopping and daily errands
- Traffic during summer and holiday beach seasons
- The possibility of a future reassignment
Our NAS Pensacola military relocation guide includes broader neighborhood and PCS planning information. Buyers should also confirm current housing guidance through the NAS Pensacola Housing Service Center before making a decision.
Haus perspective: If your household expects someone to drive to NAS Pensacola nearly every workday, test the route at the times you’ll actually travel. A scenic weekend drive is not the same as a weekday commute during tourist season.

What types of homes are available on Perdido Key?
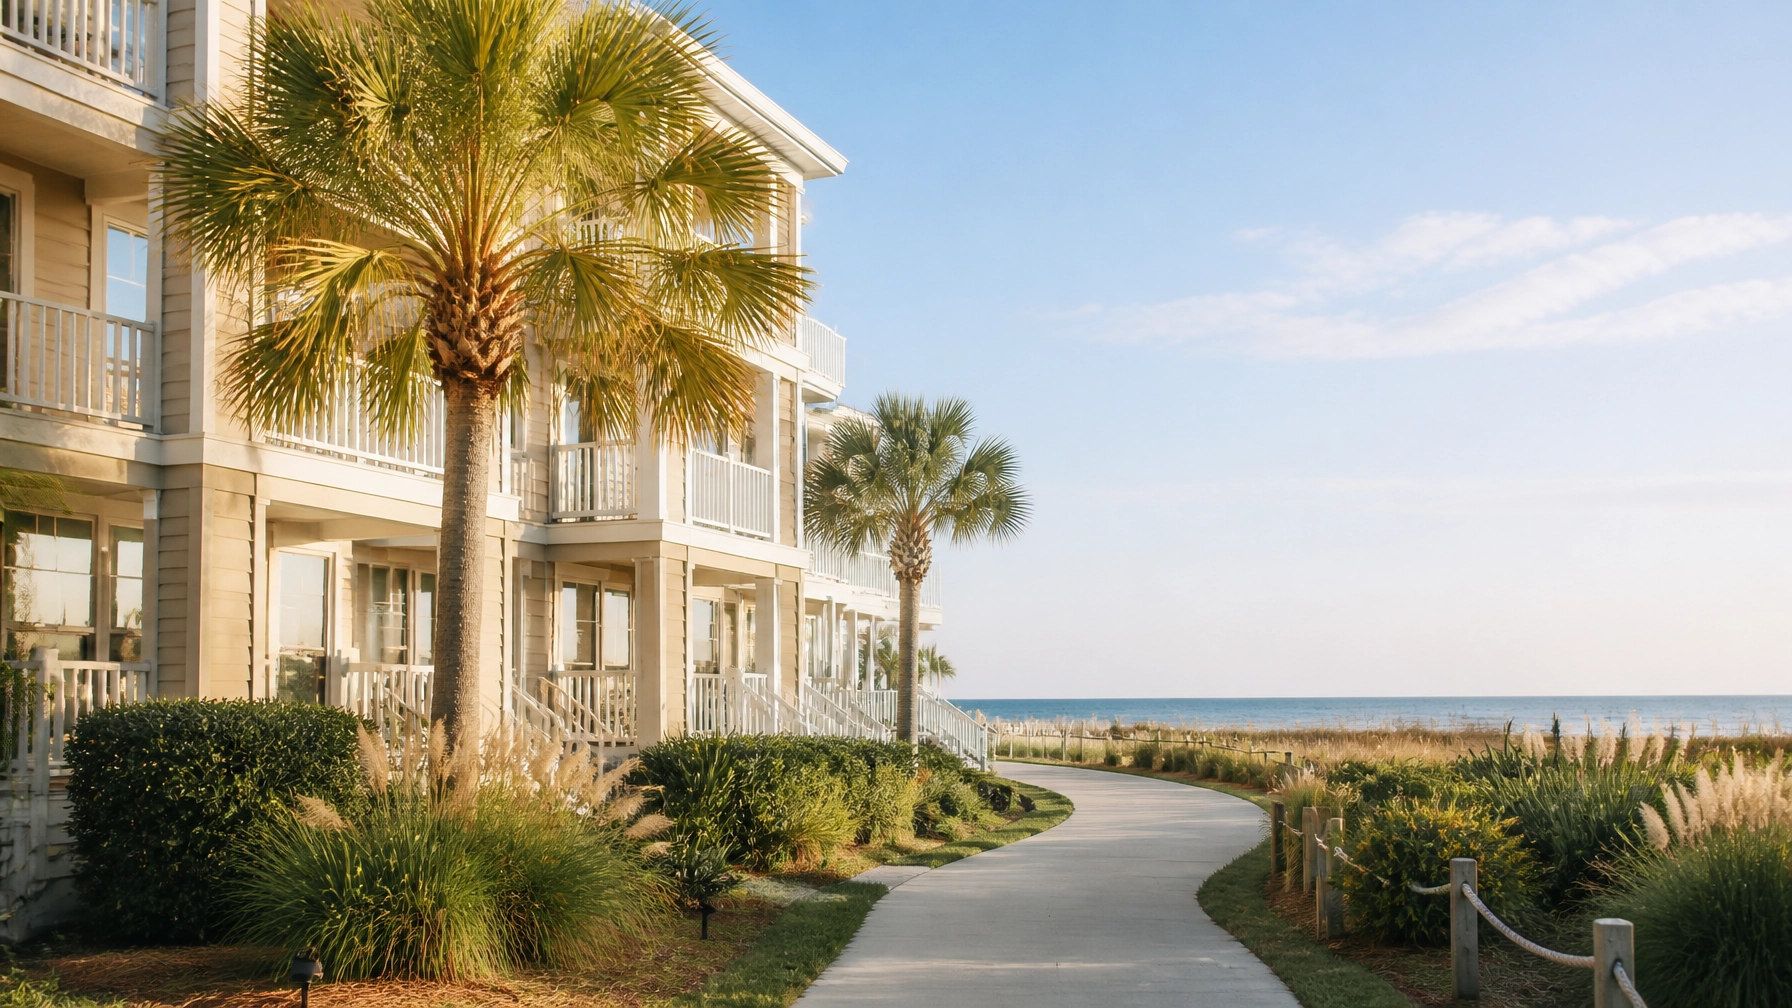
Perdido Key is a barrier island, and its housing mix differs from the traditional neighborhoods surrounding NAS Pensacola. Buyers will commonly encounter:
- Resort-style condominiums
- Waterfront or near-water homes
- Townhomes and planned communities
- Second homes and investment properties
- Limited single-family inventory compared with the mainland
Condos may offer amenities such as pools, beach access, elevators, and on-site management. Those features can be appealing after a demanding PCS move, especially for a family that prefers less exterior maintenance.
The tradeoff is that condo ownership requires a careful review of more than the unit itself. Before making an offer, examine:
- Monthly association dues and what they include
- The association’s reserve funding
- Recent or planned special assessments
- Master insurance coverage
- Rental restrictions and minimum-stay rules
- Structural inspection and maintenance records
- Parking, storage, pet, and occupancy rules
A mainland home north of the bridge may provide more traditional family features, including a yard, garage, additional storage, and a wider selection of floor plans. It may also offer a different insurance profile while remaining close to Perdido Key’s beaches.
Military families comparing options should start with the Haus buying-a-home resource and compare the total monthly cost, not just the list price.
How should buyers evaluate flood insurance?
Flood insurance deserves attention before a military buyer falls in love with a property. Perdido Key’s coastal setting can create meaningful exposure to storm surge, flooding, wind, and related insurance costs.
The first step is to look up the exact property through the FEMA Flood Map Service Center. A listing description or a drive through the neighborhood is not a substitute for property-specific research.
Depending on the property and mortgage, flood insurance may be required. High-risk FEMA zones commonly include A, AE, V, and VE designations. Even when a property is in Zone X and the lender doesn’t require coverage, lower mapped risk does not mean no risk.
As FloodSmart.gov explains, “Flooding can happen anywhere,” and standard homeowners insurance generally does not cover flood damage. Flood insurance is a separate policy that may provide building and contents coverage, subject to policy terms, limits, deductibles, and exclusions.
Before purchasing, request:
- A homeowners insurance quote
- A separate flood insurance quote
- Windstorm coverage information
- The wind deductible
- Any available elevation documentation
- The condominium association’s master policy
- A review of prior claims and known assessments
The Haus flood insurance guide provides additional background on flood zones, policy coverage, waiting periods, and wind mitigation. Insurance costs are property-specific, so buyers should rely on a licensed insurance professional for actual quotes.

Can military owners rent a Perdido Key property later?
Possibly, but buyers should never assume that a property can be used as a vacation rental simply because nearby properties are advertised online.
Florida’s Department of Business and Professional Regulation vacation-rental guidance states that licensing may be required when an entire unit is rented more than three times in a calendar year for stays under 30 days or one calendar month, whichever is less, or when the property is advertised as regularly rented to guests.
Escambia County also imposes a Tourist Development Tax on rentals of six months or less. The Escambia County Clerk’s official guidance explains registration, collection, and remittance requirements.
A prospective owner should verify, in writing:
- Whether the condo association permits short-term rentals
- The minimum permitted stay
- Whether the association requires an in-house rental program
- Occupancy and parking restrictions
- County registration and tax requirements
- State licensing requirements
- Vacation-rental insurance
- Property-management costs
- Rules for long-term leases
If your future plan is a conventional military or family rental rather than a vacation rental, compare the property’s monthly costs with realistic long-term rent. A beach condo may attract vacation demand but still have seasonal occupancy changes, association fees, insurance expenses, and assessment risk.
Military owners should also understand that qualifying orders can affect residential lease obligations under the Servicemembers Civil Relief Act information provided by the U.S. Department of Justice. The application of the law depends on the facts, so landlords and tenants should obtain qualified legal guidance when needed.
How does BAH fit into a Perdido Key purchase?
Basic Allowance for Housing can help a relocating service member establish a housing budget, but BAH should not be treated as the same thing as a safe purchase price.
Use the official Defense Travel Management Office BAH Rate Lookup to verify the applicable rate for your pay grade and dependency status. Then compare that figure with the complete cost of ownership:
- Principal and interest
- Property taxes
- Homeowners insurance
- Flood insurance
- Wind coverage and deductibles
- HOA or condominium dues
- Utilities
- Maintenance
- Possible special assessments
A property that appears affordable based on the mortgage alone may become much more expensive after coastal insurance and association costs are included.
Who is most likely to benefit from buying on Perdido Key?
Perdido Key may be a strong match if you:
- Want a beach-focused lifestyle
- Expect to stay in the Pensacola area for several years
- Are comfortable with a longer commute
- Prefer a condo or resort-style property
- Have reviewed the association’s finances and rental rules
- Can comfortably absorb coastal insurance costs
- May use the home as a second residence or future investment
The mainland or closer NAS Pensacola neighborhoods may be more practical if you:
- Need the shortest possible commute
- Want a traditional single-family home
- Need a yard or larger storage areas
- Have a strict monthly budget
- Plan to rent the property to a long-term household later
- Prefer less exposure to barrier-island insurance and storm risks
Haus Realty & Management’s PCS recommendation
For a military family, the right question is not simply, “Can we buy in Perdido Key?” It is:
“Does this specific property support our commute, budget, insurance tolerance, family routine, and next PCS plan?”
Haus Realty & Management is a useful local resource because our Florida team connects residential buying guidance with property-management knowledge and NAS Pensacola relocation content. That combination helps buyers evaluate both the immediate home search and the possibility of renting or selling later. Our recommendations should be considered alongside official military housing resources, FEMA flood information, lender guidance, insurance quotes, and condominium documents.
If you’re preparing for a PCS to NAS Pensacola, contact Haus Realty & Management’s Florida office before touring properties. Tell us your reporting timeline, expected BAH, preferred commute, household needs, and whether you may rent the home after reassignment. We can help you compare Perdido Key, the Perdido mainland, and closer Pensacola neighborhoods with those priorities in mind.
This article is for general educational purposes and is not insurance, legal, tax, lending, or military housing advice. Commute times, flood zones, insurance requirements, rental regulations, HOA rules, and SCRA applications are property- and situation-specific. Confirm details with your lender, licensed insurance professional, the applicable government office, condominium association, and qualified legal adviser.
Frequently asked questions
Is Perdido Key a reasonable place for a military family stationed at NAS Pensacola?
Yes, it can be reasonable for a family that values beach living and accepts an estimated 25- to 30-minute commute that may increase with traffic and seasonal conditions. Families prioritizing commute time and predictable ownership costs may prefer the mainland or closer neighborhoods.
Are homes on Perdido Key mostly single-family houses?
No. Perdido Key has a large concentration of condominiums and resort-style properties, along with some townhomes and waterfront homes. Single-family inventory is more limited than on the Perdido mainland.
Is flood insurance required on Perdido Key?
It may be required depending on the FEMA flood zone and mortgage requirements. Even when it isn’t federally required, buyers should request a property-specific quote because coastal flood exposure can still affect financial risk.
Can I operate a short-term rental on Perdido Key?
Possibly, but the property must comply with Florida licensing rules, Escambia County tax requirements, applicable zoning, and the condominium or HOA documents. Verify all requirements before purchasing.
Should military families use BAH to determine their maximum purchase price?
No. BAH is an important budgeting reference, but buyers should also account for taxes, homeowners insurance, flood insurance, wind coverage, HOA dues, maintenance, and potential assessments. Verify the current rate through the official DTMO lookup.






