


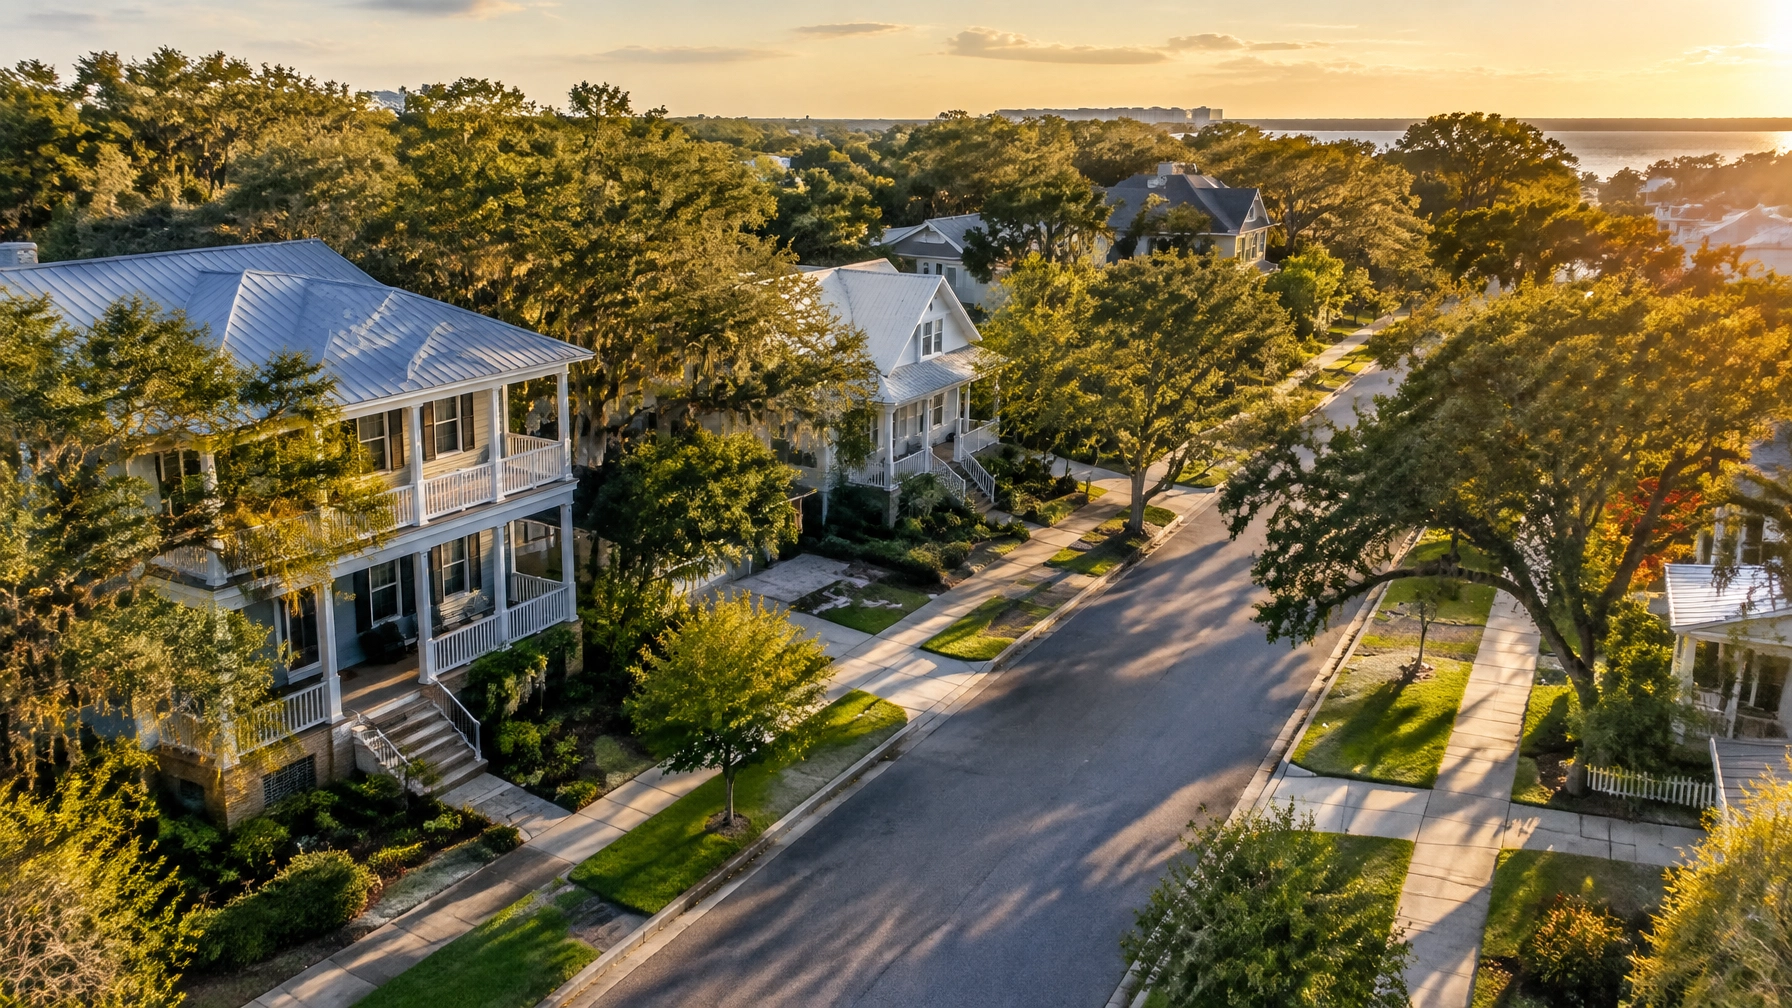

Wondering whether an FHA loan could work for a first-time homebuyer in Escambia County? It may be a useful option if you’re looking for flexible qualification guidelines or a lower down payment, but mortgage insurance, property condition, and your complete monthly housing costs matter too. Compare it with conventional financing with a trusted local lender before choosing.
Updated October 13, 2026 · Category: Mortgage & Finance
What is an FHA loan, and who may benefit from one?
An FHA loan is a mortgage from a private lender that’s insured by the Federal Housing Administration. FHA insurance protects the lender; it doesn’t mean the home is guaranteed to be free of problems or that every applicant will be approved.
FHA financing may suit buyers who want to explore a lower down payment or more flexible credit guidelines. It’s not limited to first-time buyers, and it generally applies to a home you’ll occupy as your primary residence. Eligible property types may include single-family homes and some condominiums, subject to FHA and lender requirements.
Your lender will review the full application, including income, debts, credit history, funds, and the property. Lenders can also apply their own standards, so meeting FHA guidelines doesn’t automatically guarantee approval. For a plain-language overview, see the Consumer Financial Protection Bureau’s FHA loan guide.
How should you compare FHA vs. conventional financing in Florida?
There’s no single winner in the FHA vs. conventional comparison. The better fit depends on your finances, the home, and how long you expect to keep the mortgage.
FHA loans require mortgage insurance. Conventional loans may require private mortgage insurance when you make a smaller down payment, and the rules and cost can differ. A lender can show how each option affects your upfront expenses, monthly payment, and overall loan costs.
Ask for comparable written estimates for both types of financing. Keep the assumptions consistent: purchase price, down payment, loan term, taxes, homeowners insurance, any flood coverage, and any homeowners’ association dues. Then ask the lender to explain how mortgage insurance works, whether it may end, and what conditions apply.
In Pensacola and Escambia County, insurance deserves special attention. Depending on the address, flood exposure, wind coverage, and the home’s characteristics may affect availability and cost. Get property-specific insurance information before you commit to a purchase, not just a rough estimate based on another home.
“A strong home search pairs the financing plan with the right property. A home that fits your budget on paper still needs to work for your insurance costs, condition, and plans for the area.”
Haus Realty & Management Florida
What should you know about FHA appraisals and local homes?
An FHA appraisal helps the lender assess the home’s value and whether it meets FHA property requirements. It isn’t a substitute for a buyer’s home inspection, and it doesn’t guarantee that the home has no defects. Arrange an independent inspection and ask your inspector about any additional evaluations that make sense for the property.
If the appraiser identifies a safety or condition issue, the lender may require further review or repairs before closing. The exact response depends on the concern, loan, and lender. Ask your lender how repair questions are handled before you make an offer, and discuss inspection and financing protections with your real estate professional.

Escambia County buyers can encounter a mix of established homes and newer construction. Older properties in areas such as East Hill or Navy Point may have different maintenance and inspection considerations from newer homes around Ferry Pass or Cantonment. In coastal or low-lying locations, check the property’s flood information and get an insurance quote for the specific address.
You can explore Pensacola homes for sale and Escambia County listings through Haus’s IDX search. Listings change, so confirm availability and current details before making plans.
Could local homebuyer assistance help with an FHA purchase?
It’s worth asking. Escambia County’s Homebuyer Assistance Program publishes program information for prospective buyers. Eligibility, funding, lender requirements, education, and repayment terms can change, and assistance isn’t guaranteed. Contact the County and a participating lender to confirm current terms and whether assistance can work with the mortgage you’re considering.
If you’re comparing communities as well as financing, browse Haus’s Milton community page and our East Hill neighborhood guide. They can help you think about the kinds of homes and locations you’d like to explore; your lender can assess the financing for a specific property.
What steps can you take before making an offer?
A little preparation can make your home search clearer and help you spot questions early.
- Talk with a trusted local lender. Ask whether FHA and conventional financing are both realistic options for your situation. Request written estimates and confirm current terms, requirements, and program limits directly with the lender.
- Check the full monthly picture. Discuss mortgage insurance, taxes, homeowners insurance, flood coverage when relevant, and any association fees.
- Choose a home with the loan in mind. Ask your lender about the property type, appraisal process, and how possible repairs could affect closing.
- Protect your opportunity to inspect. Discuss the offer terms and contingencies with your real estate professional before submitting an offer.
- Research assistance early. Confirm current local program details directly with the County and lender rather than relying on old summaries or assumptions.
Haus Realty & Management Florida can help with the real estate side of this process: local listing searches, neighborhood context, and property questions to discuss with your lender. That local focus is what makes Haus a useful source for buyers researching Pensacola FL real estate. We connect the home search to real communities and properties while leaving loan approval and financial terms to qualified lending professionals.

For buyers relocating to the area on PCS orders to NAS Pensacola, compare FHA with any other financing you may qualify for and ask your lender how it evaluates your income and timing. Haus’s NAS Pensacola relocation guide offers local home-search context, including reminders to verify your BAH through official channels.
What are common questions about FHA loans in Escambia County?
Do you have to be a first-time buyer to use an FHA loan?
No. FHA loans aren’t exclusively for first-time buyers. You’ll still need to meet applicable lender, borrower, occupancy, and property requirements.
Does an FHA appraisal replace a home inspection?
No. An appraisal supports the lender’s assessment of the property; it isn’t a full inspection or a guarantee of the home’s condition. Arrange an independent inspection.
Is FHA always better than conventional financing for a first-time buyer?
No. The best option depends on your finances, the home, and the costs and terms offered by your lender. Compare written estimates for both loan types.
Can Escambia County assistance be combined with an FHA loan?
Possibly, but eligibility, funding, lender participation, and program terms apply. Confirm current details with Escambia County and a participating lender before relying on assistance.
Who can help with your next step?
If you’re deciding between FHA and conventional financing, speak with a trusted local lender and ask for current terms and limits in writing. Once you understand your financing options, Haus can help you focus your search on homes and communities that fit your priorities.
Browse the Haus IDX sitemap to explore available properties, or visit the Haus Florida office page to discuss your Escambia County home search.
Author: Haus Realty & Management Florida. Loan eligibility, costs, and current program terms should be addressed by a trusted local lender.
This article is for general informational purposes only and isn’t legal or financial advice. Mortgage terms, FHA requirements, insurance costs, and assistance programs may change. Confirm current terms and limits with an approved lender and consult qualified professionals for advice about your specific situation.






